Treasury & Operations
7 Wire Transfer Alternatives for Global Payments
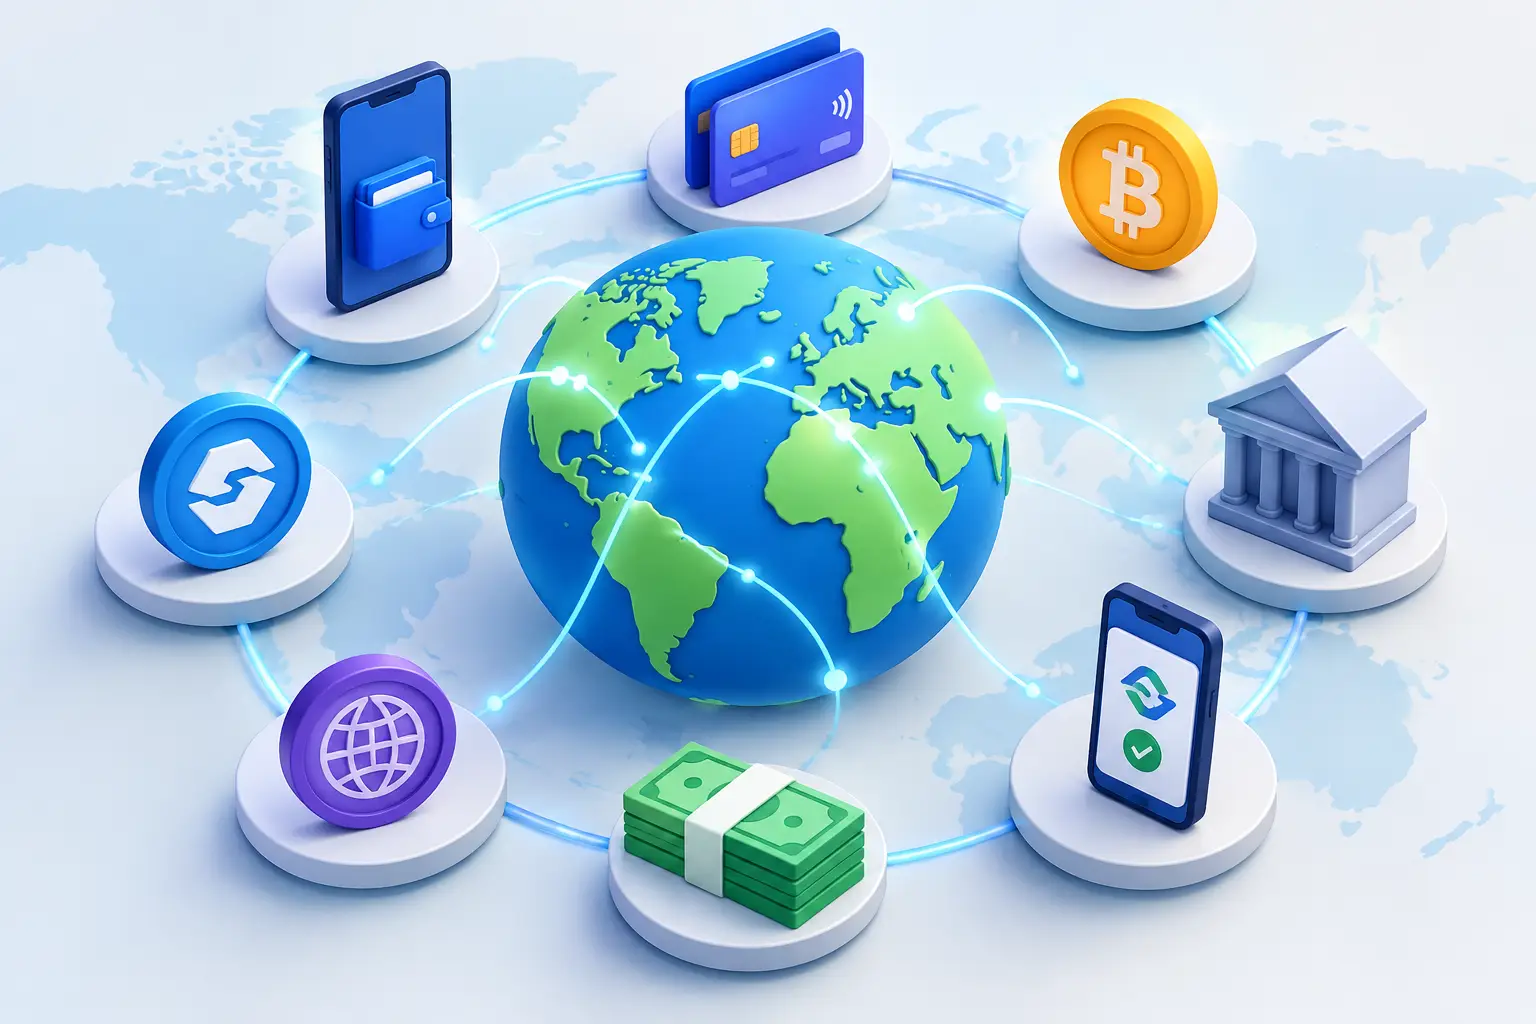
A supplier is waiting to release goods. A family member needs funds for a time-sensitive expense. A finance team must pay overseas contractors before payroll closes. In each case, traditional bank wires can work, but the cost, processing time, intermediary bank deductions, and limited tracking often create avoidable pressure. The right wire transfer alternatives can provide faster delivery, clearer FX pricing, and more practical payment options across Africa-to-global corridors.
The best choice depends on where money is going, the currency involved, the payment amount, and the level of compliance documentation required. A low-value personal transfer and a recurring business settlement should not be handled with the same payment method.
Why Businesses and Individuals Look Beyond Bank Wires
A conventional wire transfer moves money through banking networks, often involving correspondent banks when the sender and recipient do not share a direct banking relationship. That structure is established and widely accepted, particularly for high-value transfers. It can also add friction.
Fees may be charged at more than one point in the payment chain. Exchange rates can be less competitive than specialist FX providers. Processing may take several business days, especially when transactions are initiated late, require review, or pass through multiple institutions. Recipients may also receive less than expected when intermediary fees are deducted from the principal amount.
For importers, exporters, remote teams, diaspora families, and digital businesses, certainty matters as much as speed. They need to know the amount being sent, the conversion rate applied, the expected settlement timeline, and what information is needed to avoid compliance delays.
1. Licensed FX and Cross-Border Payment Platforms
For many international transactions, licensed FX and payment platforms are the most practical alternative to a bank wire. These providers combine currency conversion with payment execution, allowing users to exchange funds and send them through local or international payout routes.
The advantage is not simply convenience. A capable provider can offer a more transparent view of the exchange rate, service charge, and expected recipient amount before a transaction is confirmed. Businesses can also benefit from structured payment workflows, transaction records, and dedicated support when they are paying vendors, staff, or partners in other countries.
This option is particularly useful when a transaction involves converting African currencies to dollars, euros, pounds, or other major currencies, or receiving international funds into a local market. It is still essential to confirm supported currencies, settlement times, transaction limits, and documentation requirements before initiating payment.
ParkPay is designed for this type of need, combining FX execution, local and cross-border payment capabilities, and compliance-focused processes for individuals and businesses managing international activity.
2. Local Bank Transfers Through Domestic Payment Rails
When the sender and recipient are in the same country, or when funds can be paid out locally in the destination market, a domestic bank transfer is usually more efficient than an international wire. Local payment rails often settle faster and cost less because the payment does not need to move through a correspondent banking chain.
For example, a company receiving foreign currency may convert it through a regulated provider and pay a local supplier in local currency. The supplier receives a familiar bank deposit, while the business reduces the complexity of sending a foreign-currency wire directly.
Local transfers are not a replacement for every international payment. They are most effective when the recipient has a local account and the payment provider has established payout capabilities in that market. For routine supplier payments, local payroll, refunds, and contractor settlements, they can be a strong operational choice.
3. Multi-Currency Accounts
A multi-currency account allows an individual or business to hold, receive, and pay in more than one currency. Instead of converting every incoming payment immediately, the account holder can keep funds in the received currency and convert when the timing and rate are suitable.
This can be valuable for businesses with regular exposure to dollar, euro, pound, or other foreign-currency expenses. An import business, for instance, may receive revenue in one currency but pay overseas suppliers in another. Holding balances in relevant currencies can reduce unnecessary conversions and make cash flow planning more predictable.
The trade-off is that multi-currency accounts require disciplined treasury management. Holding a foreign currency creates exposure to exchange-rate movements. A favorable rate today may not be available next week. Businesses should define when to convert, how much to hold, and which payments require immediate funding.
4. Digital Wallets and Mobile Money
Digital wallets and mobile money services can provide fast, accessible payment delivery, especially in markets where mobile-based finance is widely used. For lower-value transfers and regular personal payments, they may be easier for recipients to access than a bank account.
This option is often helpful for families, freelancers, and small merchants who need funds quickly and prefer to receive money on a phone. In some corridors, recipients can cash out, pay bills, make purchases, or transfer funds to a bank account directly from the wallet.
However, wallet transfers may have lower transaction limits, variable fees, and restrictions on cross-border availability. They may also be less suitable for large B2B settlements, trade payments, or transactions that require detailed remittance information. Before sending, confirm the recipient's wallet provider, identity verification status, limits, and cash-out options.
5. Card-Based Payments
Corporate and virtual cards can be an effective alternative when the payment is for an online subscription, travel expense, software service, advertising account, or purchase from a merchant that accepts cards. Compared with a wire, a card payment can be authorized quickly and may provide better expense controls.
Finance teams can assign spending limits, restrict merchant categories, issue cards for specific employees, and reconcile transactions more easily. For small but frequent business expenses, this reduces the time spent creating individual payment instructions.
Cards are not ideal for every cross-border obligation. Merchants may charge processing fees, card networks apply their own exchange rates or foreign transaction fees, and large invoices may exceed card limits. A supplier that needs a direct account credit will still require a bank or local payout route.
6. Escrow and Trade Payment Arrangements
For international trade, the concern is often not just how fast money moves. It is whether both parties can perform safely. Escrow or structured trade payment arrangements can help when a buyer wants assurance that goods will be shipped and a seller wants confidence that funds are available.
Under an escrow arrangement, funds are held by an agreed third party until defined conditions are met. Those conditions may include shipping documents, inspection results, delivery confirmation, or contract milestones. This can lower counterparty risk for first-time supplier relationships and larger purchases.
The added protection comes with added process. Escrow services may cost more than a standard transfer and require clear contractual terms. They are best used when transaction value, unfamiliarity between parties, or delivery risk justifies the additional control.
7. Digital Assets for Approved Use Cases
Digital assets, including stablecoins, are sometimes used to move value across borders outside traditional bank hours. For businesses and individuals already operating in compliant digital-asset environments, they can offer quick transfer capabilities and near-continuous availability.
This route requires caution. Regulatory treatment differs by jurisdiction, wallet addresses must be verified carefully, and conversion back to fiat currency may introduce fees, liquidity considerations, and compliance checks. Stablecoins may reduce price volatility relative to other digital assets, but they are not free from issuer, platform, operational, or regulatory risk.
For commercial payments, digital assets should only be considered where both parties understand the process, the use case is legally permitted, and records are maintained for accounting and compliance purposes. They are a specialized tool, not a default replacement for regulated fiat payment infrastructure.
How to Choose Between Wire Transfer Alternatives
Start with the outcome you need, not the payment product. If the recipient needs local currency in a bank account, prioritize a provider with direct local payout capabilities. If your business is managing recurring international invoices, look for transparent FX pricing, approval controls, payment records, and reliable support. If the transaction is high value or trade-related, security and documentation may matter more than instant settlement.
Assess four practical factors before sending funds:
- The total cost, including exchange-rate margin, transfer fees, receiving fees, and possible intermediary deductions.
- The settlement time and whether it is measured in business days, calendar days, or real-time availability.
- The level of security, licensing, identity verification, transaction monitoring, and customer support available.
- The recipient experience, including accepted payout methods, account requirements, payment limits, and ability to track funds.
Do not choose solely based on the advertised transfer fee. A zero-fee payment with a weak exchange rate can cost more than a clearly priced service with a competitive rate. Likewise, the fastest option is not always the right one if it cannot provide the payment records, compliance support, or recipient certainty your transaction requires.
For cross-border payments, the strongest alternative is usually the one that makes the full transaction clear before money moves: the rate, the charges, the delivery method, the expected timing, and the documentation needed. That clarity gives individuals confidence and gives businesses the control to keep global operations moving.