Treasury & Operations
SWIFT Versus Local Payouts: Which Fits?
A supplier has delivered the goods. Payroll is due Friday. Your recipient has sent bank details and expects funds in a familiar currency. At that point, SWIFT versus local payouts is not a technical banking choice. It directly affects settlement time, fees, foreign exchange outcomes, and the confidence your recipient has in doing business with you.
For African businesses paying global partners, and international businesses paying people or suppliers in Africa, the best route depends on the payment corridor, currency, amount, urgency, and the receiving bank. A SWIFT transfer can provide broad reach for international bank payments. A local payout can make funds easier and faster for the recipient to receive. Knowing the difference helps finance teams make better decisions before a payment is released.
SWIFT versus local payouts: the core difference
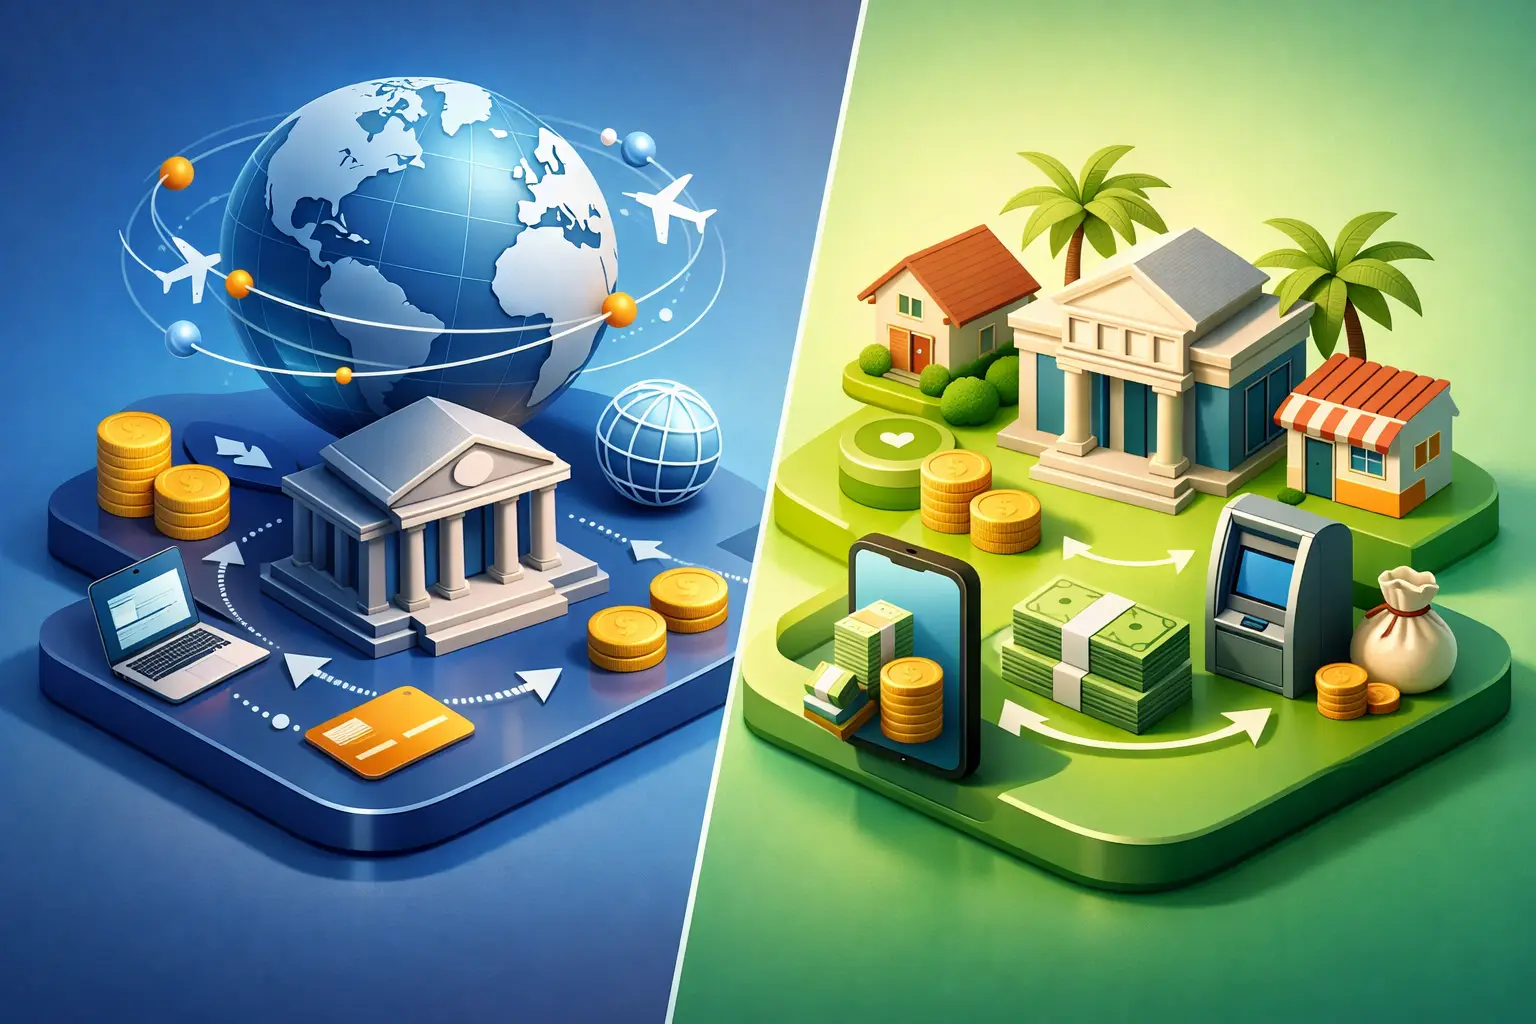
SWIFT is the global messaging network banks and financial institutions use to communicate payment instructions. When you send a SWIFT payment, the funds may move through one or more correspondent banks before reaching the beneficiary bank. It is designed for international reach and supports many currencies, making it a familiar option for cross-border trade, professional services, and high-value transfers.
A local payout, by contrast, delivers funds through the domestic payment rails of the recipient's country. The sender may initiate a cross-border transaction, but the recipient receives money as a local bank transfer in the local currency. Depending on the market, this may use account-to-account rails, instant payment networks, clearing systems, or other domestic banking infrastructure.
The practical distinction is straightforward. SWIFT moves payment instructions across international banking relationships. Local payouts aim to complete the recipient-side payment as if it were a domestic transfer. Both can be appropriate. The stronger option is the one that fits the payment objective rather than simply the one your team has always used.
When SWIFT payments make sense
SWIFT remains valuable because it provides reach. If you need to send a currency that is not easily available through a local payout route, pay a corporate beneficiary in a major financial center, or settle a large invoice with specific payment documentation, SWIFT may be the right method.
It is often suitable for importers paying overseas manufacturers, businesses settling international contracts, or organizations that need payments delivered to a specific foreign currency account. In these cases, sending funds in USD, EUR, GBP, or another agreed currency can help align the payment with the commercial contract.
SWIFT can also be preferable when the beneficiary's bank requires it or when the payment needs a detailed reference, invoice number, or supporting trade information. For high-value transactions, the traceability associated with a bank-led international payment process may be important to both parties.
However, broad reach does not always mean predictable delivery. A SWIFT transfer can involve intermediary banks, especially when the sending and receiving institutions do not have a direct relationship. Each intermediary can add processing time or deduct charges. The recipient may receive less than expected if fee handling was not clearly agreed in advance.
Where local payouts create an advantage
Local payouts are built around recipient experience and operational efficiency. When a contractor in Kenya, a supplier in Nigeria, or a consultant in another market needs funds in their local bank account, a local payout can reduce the friction of receiving an international transfer.
The recipient receives a familiar local currency and may avoid the work of converting foreign currency after the payment arrives. That matters for recurring business expenses such as payroll, vendor invoices, marketplace seller disbursements, rebates, and partner commissions. It can also reduce questions from recipients who only want to know when the funds will be available in their account.
For the sender, local payouts can offer better visibility over the final amount the recipient receives. Instead of sending foreign currency through several banks and waiting to see which fees are deducted, the sender can quote and approve the exchange rate and payout amount upfront, subject to the selected corridor and service terms.
Speed can be another benefit. Domestic payment rails may settle more quickly than a traditional correspondent banking route, particularly where real-time or same-day local transfers are available. But speed is market-specific. Local banking cutoffs, public holidays, account validation requirements, and compliance reviews can still affect timing.
Local payout limitations to consider
A local payout is not automatically the better choice for every payment. Some currencies have limited availability, local rails may have transaction caps, and a recipient may specifically require settlement in a foreign currency. A business paying for machinery from Europe, for example, may need to pay the supplier's EUR account through SWIFT rather than convert the amount into a local payout currency.
Finance teams should also confirm that beneficiary details match the requirements of the destination market. A local account number, bank code, mobile-linked identifier, or other domestic detail may be required. Getting this information right before payment approval prevents avoidable delays.
Compare the full payment cost, not only the transfer fee
The visible transfer fee is only one part of cross-border payment cost. A useful comparison includes the quoted exchange rate, possible correspondent bank charges, beneficiary fees, payment tracking effort, failed-payment risk, and the internal time spent resolving exceptions.
With SWIFT, fees can be allocated in different ways. The sender may bear all charges, charges may be shared, or the recipient may bear them. Even when the instruction is clear, intermediary deductions can make the exact received amount harder to predict. This is a concern when a supplier must receive a precise invoice total.
With local payouts, the key question is often the FX rate and the guaranteed local-currency amount. If your business has revenue in one currency and operating costs in another, a transparent rate and confirmed payout amount can improve cash-flow planning. The best rate is not simply the highest advertised rate. It is the rate that delivers the required recipient value with clear fees and acceptable execution timing.
Build the route into your payment policy
Rather than choosing payment routes case by case without a framework, businesses should define simple rules. Use SWIFT where foreign-currency settlement, global reach, or contract requirements make it necessary. Use local payouts where recipients need local currency, speed matters, and predictable receipt is a priority.
Your policy should also identify approval thresholds, required payment references, acceptable beneficiary documentation, and the compliance checks needed for each type of transaction. This is particularly important for businesses operating across Africa and global markets, where banking requirements and regulatory expectations differ by corridor.
Compliance is not a final checkbox after funds are sent. Strong identity verification, customer due diligence, sanctions screening, and transaction monitoring protect both the payer and the payment provider. They also reduce the likelihood that a legitimate payment is paused because information is incomplete or inconsistent.
Questions to ask before you send
Before selecting a route, ask what currency the recipient truly needs, whether they must receive an exact amount, how quickly the funds are required, and whether the recipient's bank can accept the chosen payment type. Confirm the full cost of conversion and delivery, not just the initial fee.
Also consider the frequency of the payment. A one-time overseas equipment purchase may justify a SWIFT transfer with detailed documentation. Monthly payments to contractors or local suppliers may benefit from a local payout structure that is easier to reconcile and repeat.
For growing businesses, this decision becomes more significant as payment volume increases. Small inefficiencies across dozens of payouts can create material FX costs, reconciliation delays, and pressure on finance teams. A payment partner such as ParkPay can help businesses combine currency conversion, cross-border settlement, local delivery options, and compliance support within a controlled operating process.
The most effective payment route is the one that lets your recipient receive the right value, in the right currency, with a clear record of what happened. Treat that outcome as part of the commercial relationship, not just a back-office task.