Treasury & Operations
KYC KYB Comparison for Cross-Border Payments
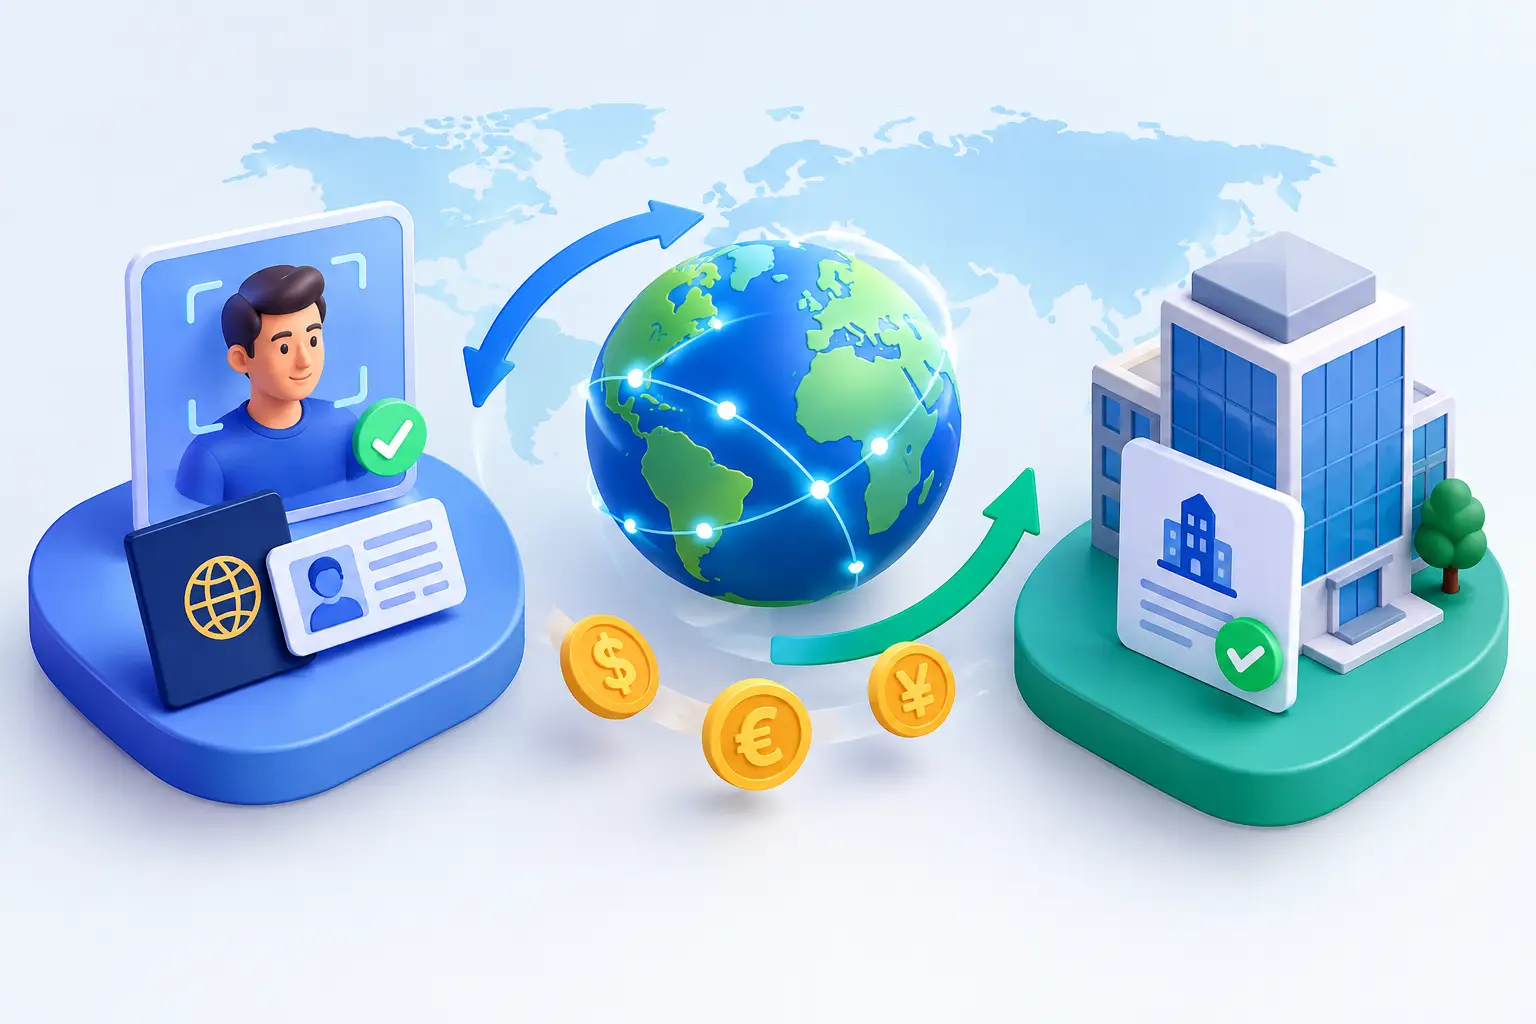
A delayed payment is rarely just a payment problem. For an importer awaiting goods, a freelancer receiving overseas income, or a finance team settling suppliers across borders, the delay often begins with incomplete customer checks. A clear KYC KYB comparison helps explain why financial providers request different information from individuals and businesses - and how getting verification right supports faster, safer transactions.
KYC vs. KYB: What Is the Difference?
KYC means Know Your Customer. It is the process financial institutions use to verify that an individual customer is who they claim to be. The goal is to prevent fraud, identity theft, money laundering, sanctions breaches, and other financial crime before an account is used for payments, foreign exchange, or digital asset activity.
KYB means Know Your Business. It applies the same principle to companies, partnerships, nonprofits, and other legal entities. Instead of verifying one person alone, KYB establishes whether a business is legitimate, understands who owns or controls it, and assesses whether its activity presents an acceptable level of risk.
The difference is straightforward: KYC verifies people, while KYB verifies businesses and the people behind them. In practice, both are necessary for trusted cross-border financial services.
For example, an individual sending funds to support family abroad may complete KYC by providing an ID document, a selfie or liveness check, and contact information. A trading company paying an overseas manufacturer may need KYB, including incorporation records, business address details, ownership information, and evidence of its commercial activity.
Why KYC and KYB Matter for International Payments
International money movement creates legitimate opportunities for trade, investment, and personal support. It can also create risk when payment providers cannot clearly identify the people and entities using their services. Funds can move across several jurisdictions quickly, often through different currencies, correspondent networks, and local payment rails.
That makes compliance more than an administrative exercise. Effective verification helps payment providers identify suspicious behavior early, meet regulatory obligations, and protect genuine customers from account misuse. It also helps businesses build credibility when they need to transact with banks, partners, suppliers, and payment platforms in other markets.
For African businesses operating globally, this is particularly relevant. An SME importing equipment from Asia, receiving customer payments from North America, or converting revenue into local currency needs payment processes that are both efficient and properly documented. Weak or incomplete compliance information can result in manual reviews, delayed settlements, rejected transfers, or restricted account access.
Strong KYC and KYB processes reduce avoidable friction. They do not eliminate every review, especially for higher-risk transactions, but they give financial providers a reliable foundation for processing activity with greater confidence.
What KYC Usually Verifies
KYC begins with collecting basic customer information and validating it against trusted sources. The exact requirements depend on the service, jurisdiction, transaction size, and risk profile, but the process commonly covers identity, location, and expected account use.
An individual may be asked for a government-issued photo ID, such as a passport, driver’s license, or national identity card. Providers may also request proof of address, a phone number, date of birth, and a selfie check to confirm that the person opening the account is the person shown on the document.
Verification does not end at onboarding. Ongoing KYC can include transaction monitoring, sanctions and politically exposed person screening, and periodic updates when a customer’s information or payment behavior changes. If someone who normally makes small personal transfers suddenly begins moving large commercial amounts, a provider may need additional context before proceeding.
This is not automatically a sign of wrongdoing. It is a risk-based control. Customers who can clearly explain the source and purpose of funds are generally better positioned to avoid unnecessary delays.
KYC for individuals using FX services
For individuals, a smooth verification experience depends on accuracy. Names should match across documents, IDs should be current and readable, and residential addresses should be entered exactly as they appear on supporting records. Small inconsistencies can create manual review work, especially when sending money internationally.
Customers should also be prepared for questions about the purpose of a payment or the source of funds for larger transactions. Salary payments, savings, asset sales, family support, and professional income are all legitimate examples, but clear supporting information makes compliance review more efficient.
What KYB Usually Verifies
KYB is more detailed because a business can have multiple owners, directors, authorized signatories, and operating locations. A registered company may appear legitimate on paper while still presenting risk through hidden ownership, fraudulent documentation, or unclear commercial activity.
A typical KYB review confirms the company’s legal name, registration number, formation date, registered address, and operational status. It also identifies directors and authorized representatives, then determines the company’s ultimate beneficial owners - the individuals who ultimately own or control the business.
Depending on the business type and payment needs, additional documents may include certificates of incorporation, constitutional documents, tax information, board resolutions, proof of trading address, invoices, contracts, bank statements, or a description of expected payment activity.
The purpose is not to create paperwork for its own sake. It is to establish who the business is, who has authority to act for it, what it does, and why its expected payment patterns make commercial sense.
Beneficial ownership is central to KYB
Beneficial ownership is one of the most important parts of a KYB review. A company’s legal shareholders are not always the people who ultimately control decisions or benefit from its funds. Financial providers need visibility beyond the company name to understand that ownership structure.
For a simple owner-managed business, this can be quick to establish. For a group with holding companies, international shareholders, or trust structures, the review may take longer. The trade-off is justified: better ownership data helps prevent bad actors from using layered corporate structures to hide illicit activity.
A Practical KYC KYB Comparison
The following distinction is useful for customers preparing to use a payments or FX platform:
- KYC subject: An individual customer or an individual connected to a business.
- KYB subject: A legal entity, plus its directors, signatories, and beneficial owners.
- KYC focus: Identity, personal address, sanctions exposure, and expected personal activity.
- KYB focus: Company legitimacy, ownership, authority, business purpose, and expected commercial transactions.
- KYC documents: Personal identification, address verification, and sometimes proof of funds.
- KYB documents: Registration records, ownership details, corporate authorization, and evidence of business operations.
A business account often requires both processes at once. The company completes KYB, while each director, account signer, or beneficial owner may undergo KYC. This combined approach allows a provider to verify the organization and the people responsible for it.
Where Verification Can Slow Down
Most verification delays are preventable. Poor-quality document images, expired IDs, mismatched names, incomplete ownership details, and unclear transaction descriptions are common causes. Businesses can also run into issues when the person applying does not have documented authority to open or manage a financial account on behalf of the company.
Cross-border activity adds another layer. Documents may come from different countries, entity records may be held in local registries, and customer information may need to be checked against global sanctions and watchlists. A provider must balance speed with the duty to investigate discrepancies.
The best approach is to submit complete, current information at the start. Businesses should maintain an accessible compliance file containing incorporation documents, ownership records, director details, and recent evidence of trading activity. Individuals should use documents that match their account details and retain records that explain significant transfers.
Building Compliance Into Payment Operations
For growing businesses, compliance should not be treated as a one-time onboarding task. Ownership changes, new product lines, expanded markets, and higher payment volumes can all affect a company’s risk profile. Keeping information current makes it easier to continue operating without interruption.
Finance teams should also align payment descriptions, invoices, and supporting documents. If a transfer is for inventory, consultancy, freight, or software services, the transaction record should tell the same commercial story as the related invoice or contract. Clear documentation supports faster review and reduces uncertainty for all parties.
ParkPay’s compliance-focused payment infrastructure is designed around this operational reality: trusted verification, clearer due diligence, and support for international transactions where security and execution both matter.
KYC and KYB are not barriers to global commerce. When handled well, they are the controls that make dependable cross-border payments possible. Prepare the right information before you need to move funds, and compliance becomes a practical advantage rather than a last-minute delay.