Treasury & Operations
Identity Verification Case Study for Cross-Border FX
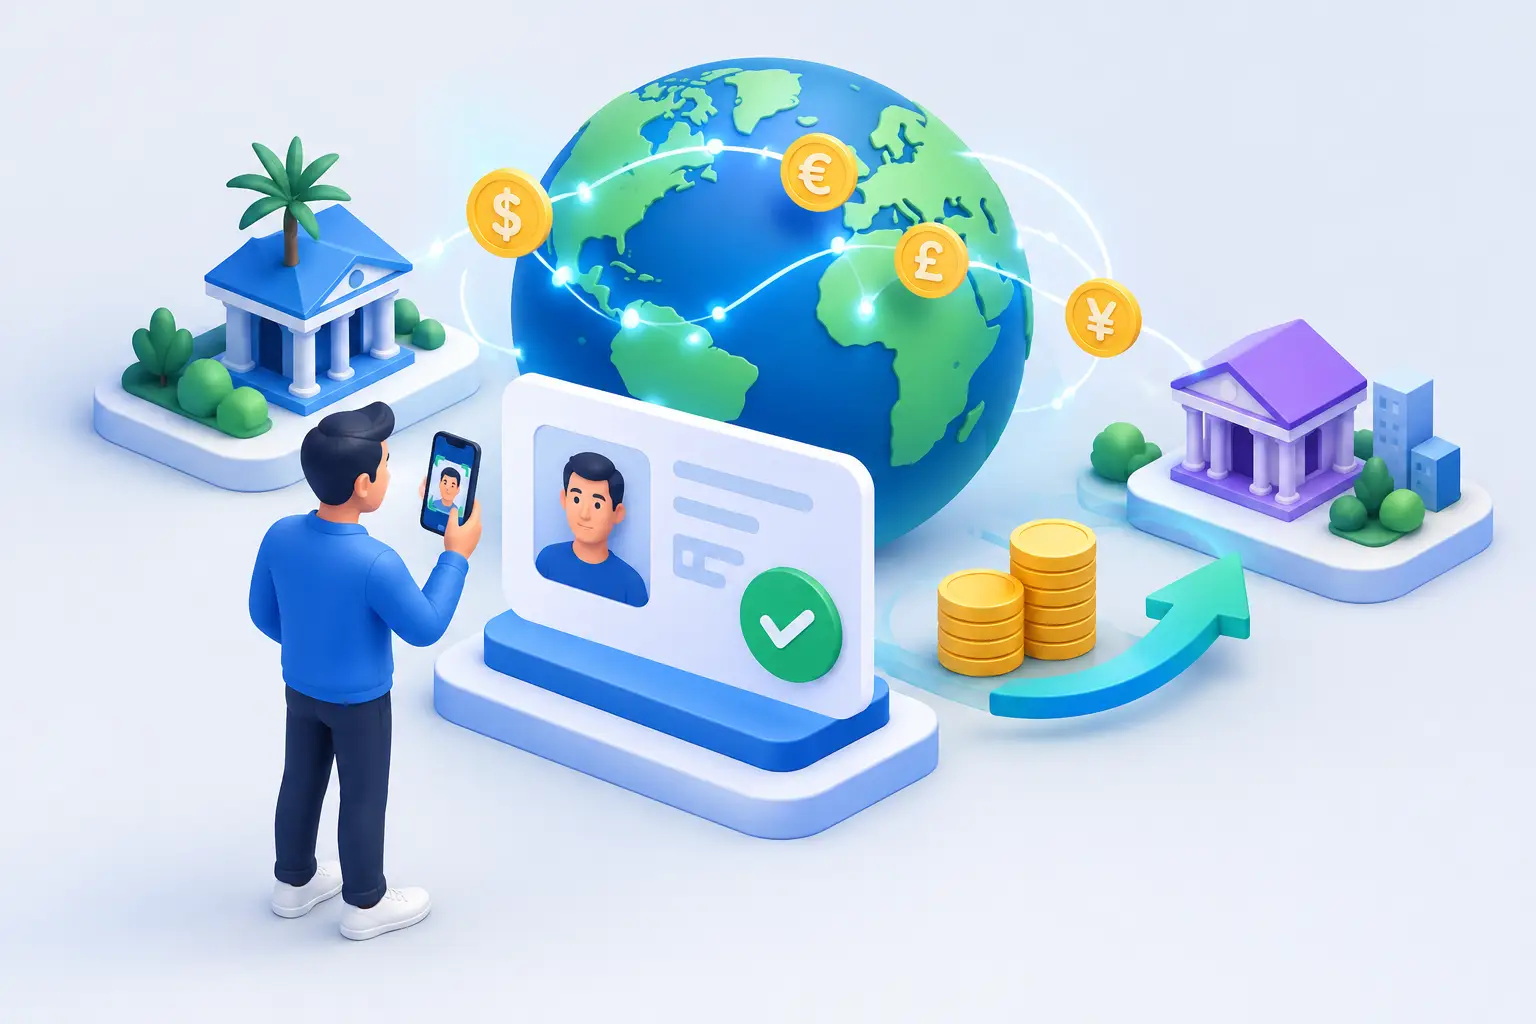
A payment can be approved in seconds, but a weak onboarding decision can create exposure that lasts for years. For African businesses moving funds to suppliers, partners, and service providers across global markets, identity verification is not a back-office formality. It is the control that determines whether fast cross-border settlement can happen with confidence. This identity verification case study examines how a structured verification process can reduce risk without turning customer onboarding into a costly delay.
The example below is a composite scenario based on common operational challenges in Africa-to-global payment corridors. It is designed to show the decisions, trade-offs, and measurable improvements a finance team can expect when verification is built into the payment journey.
The business challenge: speed without blind spots
A growing import and distribution company in West Africa was making regular payments to manufacturers in Europe and Asia. Its finance team managed supplier settlements, foreign currency purchases, and contractor payments across several jurisdictions. Transaction values varied from modest operating expenses to large inventory orders tied to shipping schedules.
The company had a practical problem. Its existing process relied on manual document collection, email reviews, and separate checks performed at different points in the customer relationship. A new business customer could submit incorporation documents and director identification, but the review team still had to determine whether the documents were current, whether the individual was authorized to act for the company, and whether the payment activity matched the stated business purpose.
This created two risks. If the team moved too slowly, legitimate customers could miss supplier deadlines or seek another FX provider. If it moved too quickly, the business could accept incomplete records, overlook inconsistent information, or process activity that required enhanced review.
The goal was not to approve every applicant faster. The goal was to make sound approval decisions faster, while ensuring higher-risk cases received the attention they required.
Identity verification case study: building a better control flow
The company redesigned its onboarding process around a simple principle: collect the right evidence once, validate it early, and use the result throughout the customer lifecycle.
For individual users, the verification flow focused on identity document checks, facial matching where appropriate, contact information validation, and screening against applicable compliance requirements. For business accounts, the process added company registration records, ownership information, authorized signatory checks, and a clear explanation of expected transaction activity.
The verification workflow was connected to the payment process through an API-based compliance layer. This meant information did not need to be re-entered manually each time a customer requested an FX conversion or cross-border transfer. Instead, the system could identify whether an account was verified, whether documents were approaching expiration, and whether a transaction required an additional review before release.
The operational change mattered because identity data was no longer treated as a static onboarding file. It became an active input in payment decisions.
A risk-based approach, not one-size-fits-all friction
The business did not apply the same review depth to every customer. A verified professional sending a routine amount for education or family support does not present the same profile as a newly formed company requesting a high-value payment to a first-time overseas beneficiary.
Low-risk cases with complete, consistent information could move through automated checks and receive timely service. Cases with missing ownership details, document mismatches, unusual payment patterns, or higher-risk corridors were routed to compliance specialists for further review.
This approach protected both customer experience and compliance quality. A fully manual process can feel safe, but it often creates bottlenecks and inconsistent decisions. Fully automated approval can improve speed, but it may fail when context is needed. The right balance depends on the customer type, transaction profile, regulatory obligations, and quality of available data.
The results the team targeted
Within the composite scenario, the redesigned workflow produced clear operational benefits. Verification turnaround for straightforward individual cases moved from several business hours to a matter of minutes, subject to successful document and screening checks. Business onboarding still required more review, but the team reduced duplicate requests for documents because information was captured in a structured format from the start.
The finance and compliance teams also gained a clearer audit trail. Each decision recorded the documents submitted, the checks completed, any exceptions identified, and the reviewer action taken. When a customer asked why a payment needed more information, the support team could give a precise answer instead of sending a generic delay notice.
Most importantly, the company improved its ability to distinguish between normal urgency and genuine risk. An importer needing to pay before a supplier releases goods may require fast action. That urgency should not remove verification requirements, but a well-designed process prevents it from automatically becoming a delay.
What made the process effective
The strongest improvement was not a single verification tool. It was the way people, policy, and technology worked together.
First, the company defined what a complete customer profile looked like before asking customers to submit information. This reduced back-and-forth and made requirements easier to explain. Second, it established escalation rules for exceptions. A document mismatch, a change in ownership, or a large departure from expected transaction behavior triggered a defined review path rather than an improvised decision.
Third, the business monitored verification performance as an operational metric. Approval rates, review times, document failure reasons, and repeat customer verification status were reviewed alongside settlement speed and FX execution. That helped management see whether friction came from customer error, unclear requests, poor document capture, or a control that needed refinement.
For a cross-border payments provider, this is where technology can create a real commercial advantage. API-based verification tools can support data capture, validation, screening, and recordkeeping at scale. They do not replace professional judgment. They give compliance teams better information and more time to focus on exceptions that deserve investigation.
Applying the lesson to Africa-to-global payments
Cross-border transactions involving African markets can require additional care because documentation standards, identity systems, business registration records, and banking practices vary by country. A process designed only for one market can create unnecessary rejection rates when it is applied elsewhere without local understanding.
That does not mean standards should be lowered. It means verification should be designed for the realities of the corridors being served. Customers need clear document requirements, practical ways to provide information, and timely communication when an application needs more evidence. Compliance teams need reliable records, consistent policies, and the ability to assess beneficial ownership and transaction purpose when the risk level calls for it.
For SMEs, this is particularly valuable. Many legitimate businesses do not have large finance departments or time to navigate fragmented onboarding across banks, FX providers, and payment platforms. A provider that combines payment infrastructure, currency conversion, and compliance support can reduce administrative burden while maintaining the safeguards international transactions demand.
ParkPay's approach to compliance services reflects this need: verification should support secure movement of money, not become an unexplained obstacle to it. Clear requirements, automated checks, and accessible human support make a meaningful difference when a customer has a supplier deadline or a business operation depending on settlement.
Questions finance teams should ask
Before selecting an identity verification process or provider, a business should look beyond the headline claim of fast onboarding. The more useful question is whether the process remains reliable when a transaction becomes complex.
Can the provider verify both individuals and businesses? Can it identify authorized representatives and beneficial owners? Is there a documented process for expired documents, incomplete records, and higher-risk transactions? Can the team retrieve a clear audit record if a payment is reviewed later? And when automation cannot resolve an issue, is there a trained support or compliance team available to help?
The answers affect more than onboarding. They influence payment release times, customer confidence, operational workload, and the business's ability to meet its own regulatory obligations.
A strong verification program should feel almost invisible for legitimate, well-documented customers. When more information is needed, the request should be specific, proportionate, and explained clearly. That is how cross-border payments stay both swift and secure: not by removing controls, but by making every control purposeful.